For hospitality businesses, Christmas and New Year can be the most profitable and the most dangerous time of year. Longer trading hours, packed venues, temporary staff, higher foot traffic, and increased alcohol service all combine to significantly raise risk.
While many owners focus on maximising revenue during the festive period, insurance is often overlooked until something goes wrong. Unfortunately, that is when gaps in cover become expensive.
The Festive Season:
Peak Revenue, Peak Risk
From cafés and restaurants to bars, pubs, and event venues, the Christmas and New Year period usually means:
- More customers and faster service under pressure
- More spills, wet floors, and crowded walkways
- Temporary and casual staff stepping in
- Extended trading hours
- Private functions, Christmas parties, and New Year celebrations
With more activity comes a higher chance of customer injuries, property damage, staff incidents, alcohol related claims, and business interruption during peak trading.
Common Holiday Claims
In Hospitality
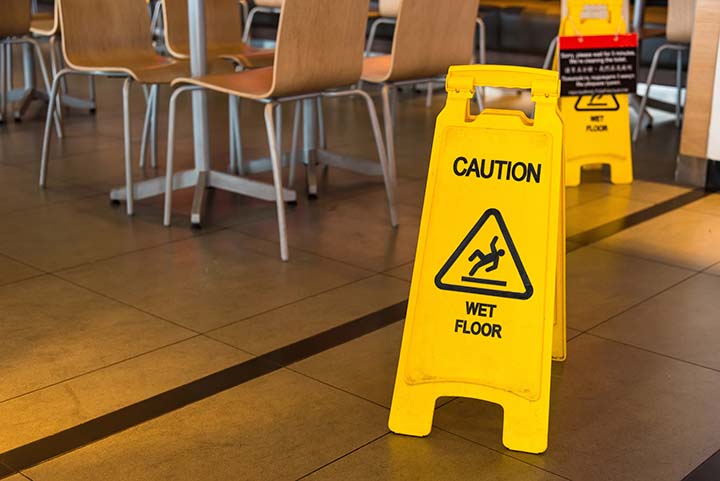
Slip and fall accidents
Wet floors from spilled drinks, rain, and increased foot traffic often lead to claims under public liability insurance.
Alcohol related incidents
Festive celebrations increase the risk of injuries involving intoxicated patrons, property damage, and allegations of negligent service of alcohol.
Staff injuries
Temporary staff may be unfamiliar with procedures, equipment, or safety protocols, increasing the likelihood of workplace incidents.
Property damage and theft
Busy venues and late night trading can lead to equipment damage, theft, vandalism, or break ins after hours.
Why Standard Cover
May Not Be Enough
Many hospitality businesses assume their policy automatically covers festive trading conditions. This is not always the case.
- Turnover estimates may not reflect holiday revenue
- Public liability limits may be too low for peak crowds
- Events and functions may not be disclosed
- Alcohol related exclusions may apply
- Staffing changes may create gaps in cover
If your policy does not reflect how you operate during Christmas and New Year, you may be exposed when you need protection most.
Key Covers
To Review Before Christmas
Public Liability Insurance
A critical cover for hospitality venues, especially during peak trading. Learn more about public liability insurance.
Workers Compensation
If you are bringing on additional staff, it is essential your workers compensation arrangements are compliant and up to date.
Business and Property Insurance
Busy periods increase wear and tear on equipment. Reviewing your business insurance and, where applicable, commercial property insurance can help avoid underinsurance.
Business Interruption Insurance
If an incident forces you to close during the festive season, lost revenue can be significant.
Christmas Events
Private Functions and Extended Trading
If you are hosting Christmas parties, private functions, ticketed events, or trading longer hours, these activities should be disclosed to your insurer. If they are not, claims may be reduced or denied.
FAQs About
Hospitality Insurance
Yes, in many cases. Special events, private functions, extended trading hours, and increased capacity should be disclosed so your policy reflects how you actually operate.
Slip and fall incidents are one of the most common, particularly during busy periods with wet floors and high foot traffic.
Coverage depends on how staff are engaged and whether your insurance arrangements match your staffing structure.
Some policies include exclusions or conditions related to alcohol service. This is especially important to review during high volume festive trading.
If you have business interruption cover in place and the closure results from an insured event, it may help cover lost income.