Food delivery apps have become a major part of café life.
For many café owners, platforms like Uber Eats and DoorDash are no longer an optional extra, they’re an important revenue stream.
They help you reach more customers, increase order volume, and keep sales moving outside traditional dine-in trade.
But there’s one important question many café owners forget to ask:
Does your café insurance actually cover delivery orders?
The answer isn’t always simple.
If your business has changed from dine-in and takeaway to app-based delivery, your insurance may need to change too.
Why Delivery Apps Can Change
Your Insurance Risk
When your café starts using delivery platforms, your operations change.
You’re no longer just serving customers at the counter or tables. You may now be managing:
- More takeaway packaging
- Higher kitchen output
- Delivery driver pickups
- Food safety during transport
- Customer complaints from off-premises orders
- Platform-related disputes
- Potential product liability claims
Even though the customer may never step inside your café, your business could still be exposed if something goes wrong with the food you prepared.
That’s why food delivery should be considered as part of your insurance review.
The Big Misconception:
“The Delivery Platform Covers Everything”
Many café owners assume:
“Uber Eats or DoorDash handles the delivery, so they must cover the risk.”
But that assumption can be dangerous.
Delivery platforms may have their own terms, conditions, and insurance arrangements, but that doesn’t automatically mean your café is protected for every possible issue.
Your café may still be responsible for things like:
- Food contamination
- Incorrect orders causing allergic reactions
- Packaging issues
- Product quality complaints
- Food-related illness
- Injuries or incidents involving delivery drivers on your premises
In other words, just because a third-party platform is involved doesn’t mean your liability disappears.
hat Could Go Wrong
With Delivery Orders?
Delivery orders create risks that café owners may not face in the same way with dine-in customers.
Food Poisoning
or Contamination Claims
If a customer becomes sick after eating food from your café, they may make a claim against your business, even if the food was delivered by a third party.
The issue may relate to:
- Food preparation
- Storage
- Temperature control
- Cross-contamination
- Packaging
Your insurance needs to respond to product liability risks, not just customer injuries on-site.
Allergy and Incorrect
Order Issues
Allergy-related claims can be serious.
For example:
- A customer requests a dairy-free meal
- The order is prepared incorrectly
- The customer has an allergic reaction after delivery
Even though the order was placed through an app, the responsibility may still come back to the café that prepared the food.
This is why processes, documentation, and insurance all matter.
Delivery Driver Incidents
at Your Premises
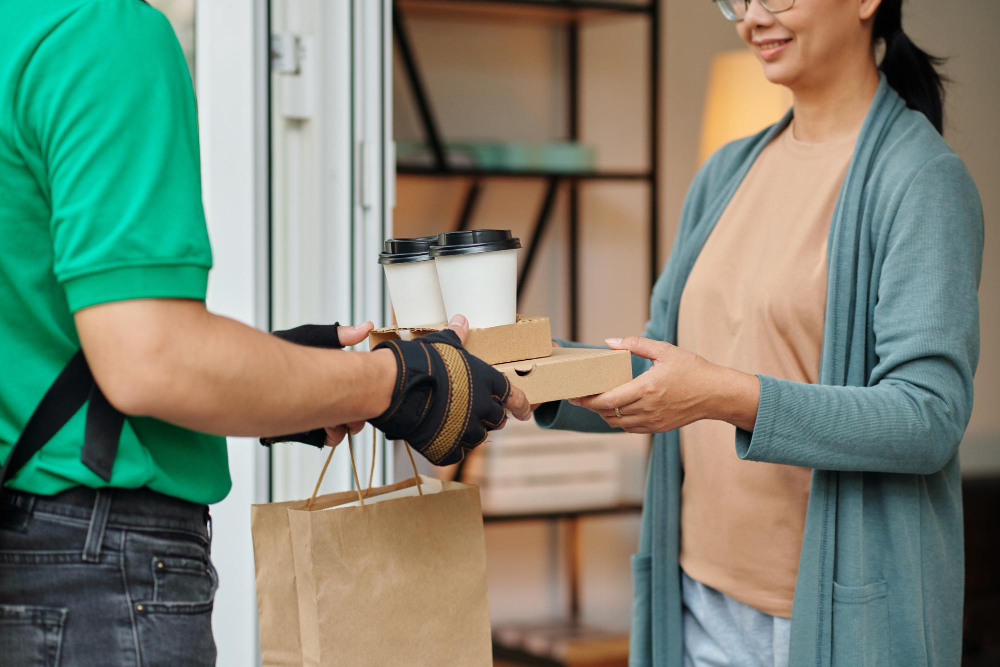
Delivery drivers often enter your café or pickup area during busy periods.
That creates potential public liability risks, including:
- Slips and falls
- Burns from hot drinks
- Trip hazards near pickup counters
- Injuries caused by overcrowded service areas
If a delivery driver is injured while collecting an order, your café could be drawn into a claim.
Packaging
and Spillage Claims
Hot drinks, soups, sauces, and takeaway meals can create risk during delivery.
Claims may arise if:
- Packaging fails
- Hot liquid spills
- Food leaks and damages property
- Items are not sealed correctly
Depending on the circumstances, liability could be disputed between the café, the delivery driver, and the platform.
Does Public Liability Insurance
Cover Delivery Apps?
Public liability insurance generally protects your business if a third party suffers injury or property damage due to your business activities.
But the key phrase is:
Due to your business activities.
If delivery is now part of your business activity, your insurer should know.
Some policies may cover takeaway and delivery-related risks, while others may have limitations or require disclosure.
The important point is this:
Don’t assume delivery orders are automatically covered. Confirm it.
Product Liability:
The Cover Café Owners Often Overlook
Product liability insurance is particularly important for cafés using delivery apps.
It can help protect your business if a product you sell or supply causes injury, illness, or damage.
For cafés, this can include claims related to:
- Food poisoning
- Contaminated food
- Incorrect ingredients
- Allergy reactions
- Defective packaging
Product liability is often included with public liability insurance, but the details matter.
You should check:
- Is product liability included?
- Are food-related claims covered?
- Are takeaway and delivery orders included?
- Are there any exclusions that apply?
What About Your
Own Delivery Drivers?
There’s a big difference between using a third-party delivery app and sending your own staff to deliver orders.
If your café uses employees or contractors to deliver food, you may need to review:
- Commercial motor insurance
- Workers compensation
- Public liability
- Personal accident cover
- Employment arrangements
- Vehicle usage disclosures
A personal car insurance policy may not cover commercial delivery use.
This is a common gap that can cause problems at claim time.
Why Your Insurer Needs to Know
About Delivery Platforms
Insurance policies are based on what your business does.
If your café was originally insured as a dine-in café, but now a large portion of revenue comes from delivery platforms, that may be a material change.
Your insurer may want to know:
- Whether you use third-party platforms
- What percentage of sales come from delivery
- Whether you use your own drivers
- Whether alcohol is delivered
- What food safety procedures are in place
- Whether orders are packaged on-site
Failing to disclose changes in your operations can create issues if a claim occurs.
The Revenue Question:
Why Delivery Sales Matter
Another issue café owners often overlook is turnover.
Insurance premiums are often partly based on declared revenue.
If Uber Eats, DoorDash, and other delivery platforms increase your total sales, your declared turnover may need to be updated.
If your revenue is understated, you could face issues such as:
- Incorrect premium calculation
- Underinsurance concerns
- Claim disputes
- Reduced claim payments in some circumstances
Your insurance should reflect how your business actually trades today and not how it traded when the policy was first arranged.
Common Insurance Gaps
for Cafés Using Delivery Apps
Café owners should watch for:
- Delivery activities not disclosed
- Product liability not properly understood
- Own-driver deliveries not covered correctly
- Turnover not updated
- Alcohol delivery not declared
- Packaging and takeaway risks overlooked
- Allergy procedures not documented
- Policy exclusions not reviewed
These gaps are easy to miss, but they can become expensive when a claim happens.
Questions Every Café
Owner Should Ask
If your café uses Uber Eats, DoorDash, or other delivery platforms, ask:
- Have I told my insurer about delivery app sales?
- Does my policy cover takeaway and delivery food?
- Is product liability included?
- Are allergy-related claims covered?
- Do I use my own drivers at any point?
- Is my declared turnover up to date?
- Are delivery drivers entering my premises safely?
- Do I understand my policy exclusions?
If you’re unsure about any of these questions, it’s time for a review.
Café Insurance Australia:
Delivery Has Changed the Risk
Food delivery has created new opportunities for cafés, but also new exposures.
The way people buy food has changed.
Your insurance needs to keep up.
At Bunker Insurance, we help café owners understand how delivery platforms, takeaway sales, and changing operations may affect their insurance.
We can help you review:
- Public liability insurance
- Product liability insurance
- Business insurance
- Workers compensation considerations
- Commercial motor exposure
- Policy exclusions
- Turnover declarations
Talk to a Broker
Who Understands Hospitality
Delivery apps can be great for business.
But they shouldn’t create hidden insurance gaps.
Speak with a Bunker Insurance advisor today and make sure your café insurance properly reflects the way your business actually operates, dine-in, takeaway, delivery, and everything in between.